How to Find and Verify Your Chase Checking Account Number on a Check
GPT_Global - 2026-09-14 11:03:19.0 39
are **30 unique, non-repeated, and practically relevant questions** related to finding or verifying a **Chase checking account number on a check**, each addressing distinct scenarios, concerns, or nuances:1. Where exactly is the Chase checking account number located on a personal check?
For remittance businesses processing U.S.-based ACH or wire transfers, accurately identifying a Chase checking account number from a physical or digital check is critical—errors cause delays, fees, and compliance risks. Unlike routing numbers, which are standardized per bank, account numbers vary per customer and must be extracted precisely. The Chase checking account number appears in the bottom MICR line—the magnetic ink character recognition strip—but *not* as the first or last set of digits. It’s the middle group (typically 10–12 digits), flanked by the 9-digit ABA routing number (left) and the 4-digit check number (right). Confusing it with the check or routing number is a common source of failed transactions. Remittance providers should train staff to verify account numbers using Chase’s official formatting: no dashes, spaces, or leading zeros—even if printed that way on the check. Always cross-check against the account holder’s ID and prior successful transfers. Chase does not publish account numbers elsewhere on the check (e.g., top corner or memo line), eliminating guesswork. Importantly, Chase never displays full account numbers on mobile deposit images due to security—so paper checks remain the only reliable source for verification. For high-volume operations, integrating optical character recognition (OCR) tools trained specifically on Chase MICR patterns can reduce manual errors by over 70%. Accuracy here directly impacts SLA adherence and client trust.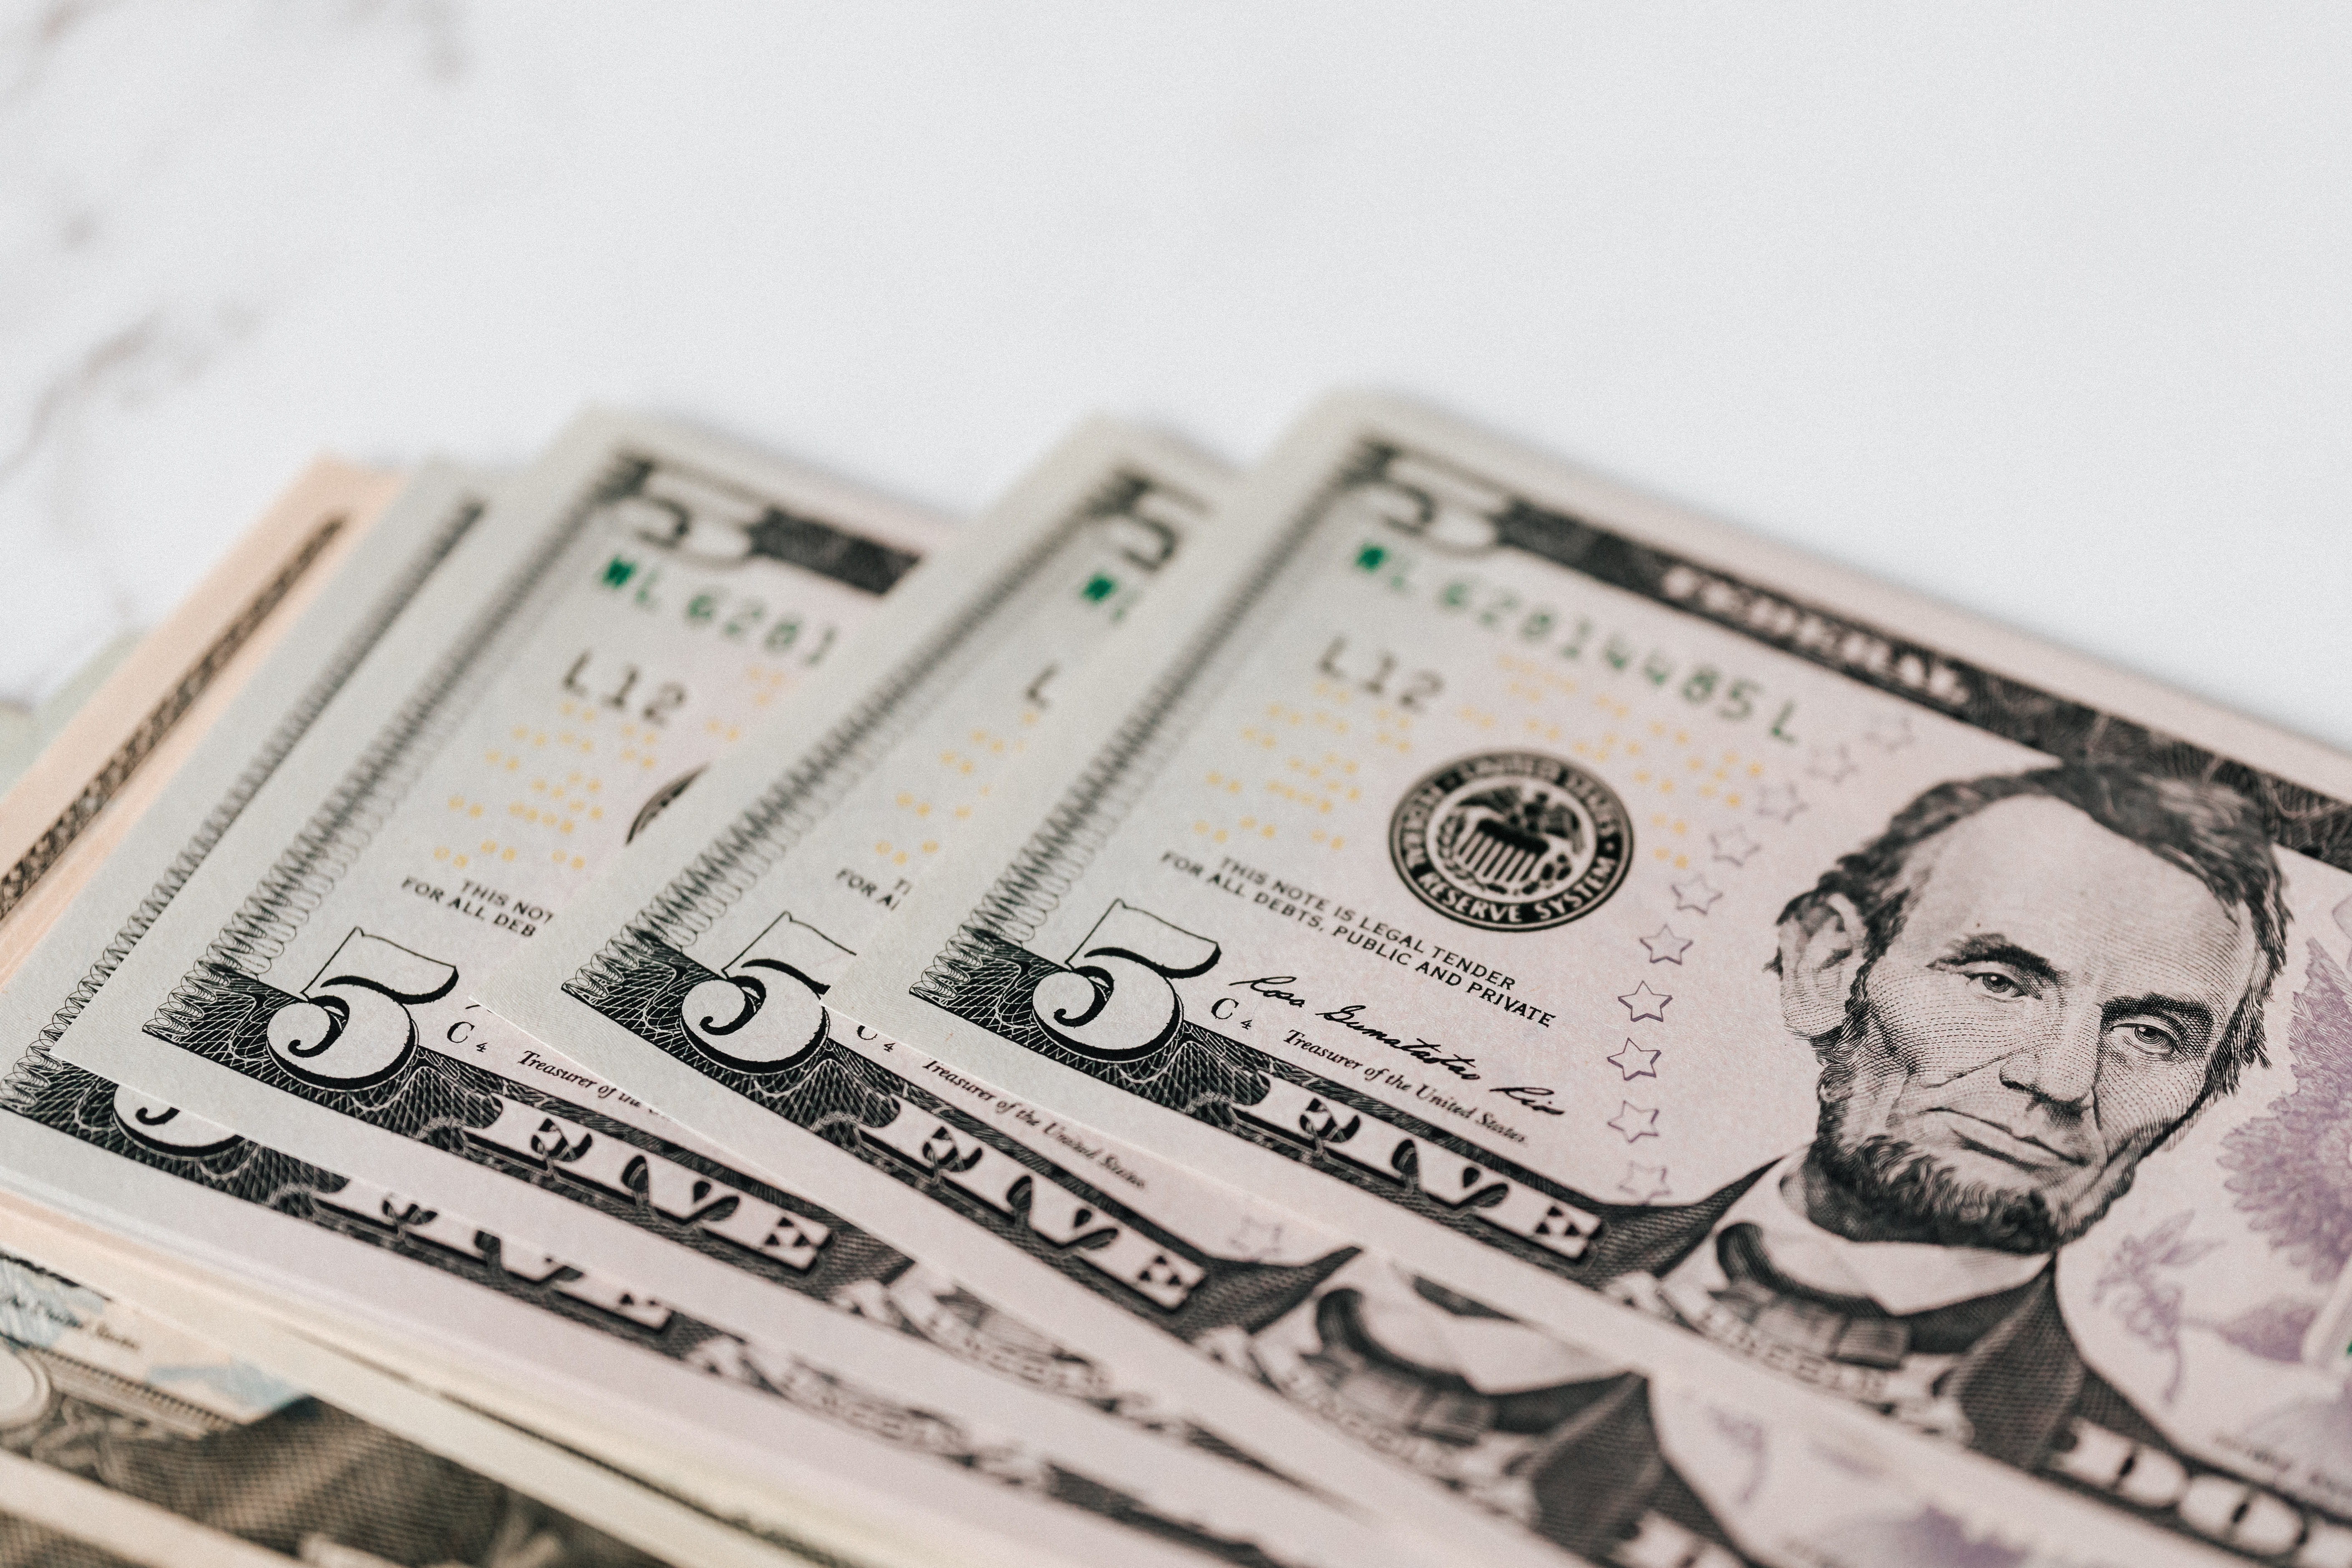
How do I distinguish the Chase account number from the routing number and check number on a check?
When sending money internationally or domestically via bank transfer, accurately identifying Chase account numbers, routing numbers, and check numbers is essential to avoid costly delays or failed remittances. The routing number—always nine digits—is printed in the bottom-left corner of a Chase check and identifies the specific financial institution and branch. It’s required for ACH transfers and direct deposits. The Chase account number appears next to the routing number (center-bottom), typically 10–12 digits long. This unique identifier links directly to your personal or business checking account and must be entered precisely when initiating a wire or ACH remittance. Mistaking it for another field risks funds going to the wrong account. The check number sits in the bottom-right corner—usually four to six digits—and tracks individual checks for reconciliation. While helpful for internal recordkeeping, it’s irrelevant for electronic remittances and should never be used in place of the account or routing number. For remittance businesses, training staff and educating clients on these distinctions minimizes errors, enhances compliance, and accelerates settlement times. Always verify numbers against Chase’s official online banking portal—not just the check—to prevent fraud or misrouting. Accurate data entry ensures faster, safer, and more reliable cross-border payments.Is the Chase checking account number printed on both the top and bottom of the check?
When sending money internationally through remittance services, accurate bank account details are critical to avoid delays or failed transfers. One common question among users is: “Is the Chase checking account number printed on both the top and bottom of the check?” The answer is no—Chase, like most U.S. banks, does not print the full checking account number on the top of the check. Instead, it appears only within the magnetic ink character recognition (MICR) line at the bottom, alongside the routing number and check number. This distinction matters for remittance providers who rely on check imaging or manual data entry. Misreading or mistyping the account number—especially when confusing it with the check number or memo field—can lead to incorrect deposits or transaction rejections. Always verify the account number directly from the MICR line (the series of numbers at the very bottom), where it sits between the 9-digit routing number (leftmost) and the check number (rightmost). For seamless cross-border payments, customers should share their Chase account details via secure digital channels—not by uploading checks unless explicitly requested. Remittance businesses benefit from educating clients on this nuance to reduce support tickets and improve first-time transfer success rates. Double-checking account formatting helps ensure compliance, speed, and trust in every transaction.Why does my Chase check show two different numbers in the MICR line—how do I know which one is my account number?
When sending international remittances, accurately identifying your Chase bank account number is critical—especially when using paper checks as a funding source. Many customers notice two distinct numbers in the MICR line at the bottom of their Chase check: one on the left (routing number) and one on the right (account number). The 9-digit routing number identifies Chase’s financial institution, while your unique account number appears immediately before the check number, typically 10–12 digits long. For remittance businesses, misreading these digits can cause failed or delayed transfers, compliance flags, or even returned payments. Always verify your account number by cross-referencing it with your Chase online banking dashboard or monthly statement—not just the check. Never use the check number (far right) or the transit/routing number (far left) as your account identifier. Chase also offers digital alternatives like ACH debit authorizations or wire instructions that eliminate MICR confusion altogether—ideal for high-volume remittance providers seeking accuracy and speed. Integrating real-time account validation APIs further reduces errors and enhances KYC/AML compliance. Clarity here isn’t just convenient—it’s foundational to secure, compliant cross-border payments.Does Chase print the full checking account number on every check, or is it sometimes truncated for security?
When processing international remittances, verifying bank account details accurately is critical—especially when receiving funds via U.S.-based checks. Many remittance businesses wonder: *Does Chase print the full checking account number on every check, or is it sometimes truncated for security?* The answer is clear: Chase **does not display the full checking account number** on standard personal or business checks. Instead, only the last four digits appear in the MICR line at the bottom—alongside the routing number and check number—while the full account number remains hidden from view. This truncation is a deliberate security measure designed to reduce fraud risk and protect sensitive financial data. For remittance providers, this means relying solely on checks for full account verification is insufficient. Always cross-reference account details through secure, verified channels—such as direct confirmation with the sender or encrypted bank statements—before initiating payouts. Understanding Chase’s check formatting helps remittance businesses strengthen compliance, prevent errors, and build client trust. It also underscores the importance of integrating multi-factor verification into your ACH or check-cashing workflows. Partnering with banks that support secure API-based account validation further enhances accuracy and reduces chargeback exposure—key priorities in high-volume cross-border payments.
About Panda Remit
Panda Remit is committed to providing global users with more convenient, safe, reliable, and affordable online cross-border remittance services。
International remittance services from more than 30 countries/regions around the world are now available: including Japan, Hong Kong, Europe, the United States, Australia, and other markets, and are recognized and trusted by millions of users around the world.
Visit Panda Remit Official Website or Download PandaRemit App, to learn more about remittance info.
Latest News

2026-10-21 19:35
2026-10-21 19:35