Contactless ATMs: NFC Cards vs Phones, Foreign Cards, Accessibility & Locations
GPT_Global - 2026-10-08 05:01:17.0 9
Do I need to enable anything in my mobile banking app to use contactless ATMs?
As remittance businesses increasingly adopt contactless ATM solutions, customers often ask: “Do I need to enable anything in my mobile banking app to use contactless ATMs?” The short answer is—yes, in most cases. Contactless ATM access relies on your bank’s digital infrastructure, and enabling features like NFC (Near Field Communication), mobile wallet integration (e.g., Apple Pay or Google Pay), and remote card controls is typically required. For remittance senders and recipients—especially migrant workers and cross-border families—this setup ensures faster, safer cash withdrawals without physical cards. Most major banks now support contactless ATM functionality via their mobile apps, but users must manually activate it under security or card settings. Some apps also require biometric authentication (fingerprint or facial recognition) for added protection during transactions. At your remittance business, proactively guiding clients through this simple activation step boosts user confidence and reduces support queries. Highlighting compatibility with local and international banking partners further strengthens trust. Always remind users to verify that their sending and receiving banks support contactless ATMs—coverage varies by region and institution. Enabling contactless ATM access isn’t just convenient—it’s a critical part of modern, secure, and inclusive financial inclusion. Make it easy for your customers, and watch transaction satisfaction—and loyalty—rise.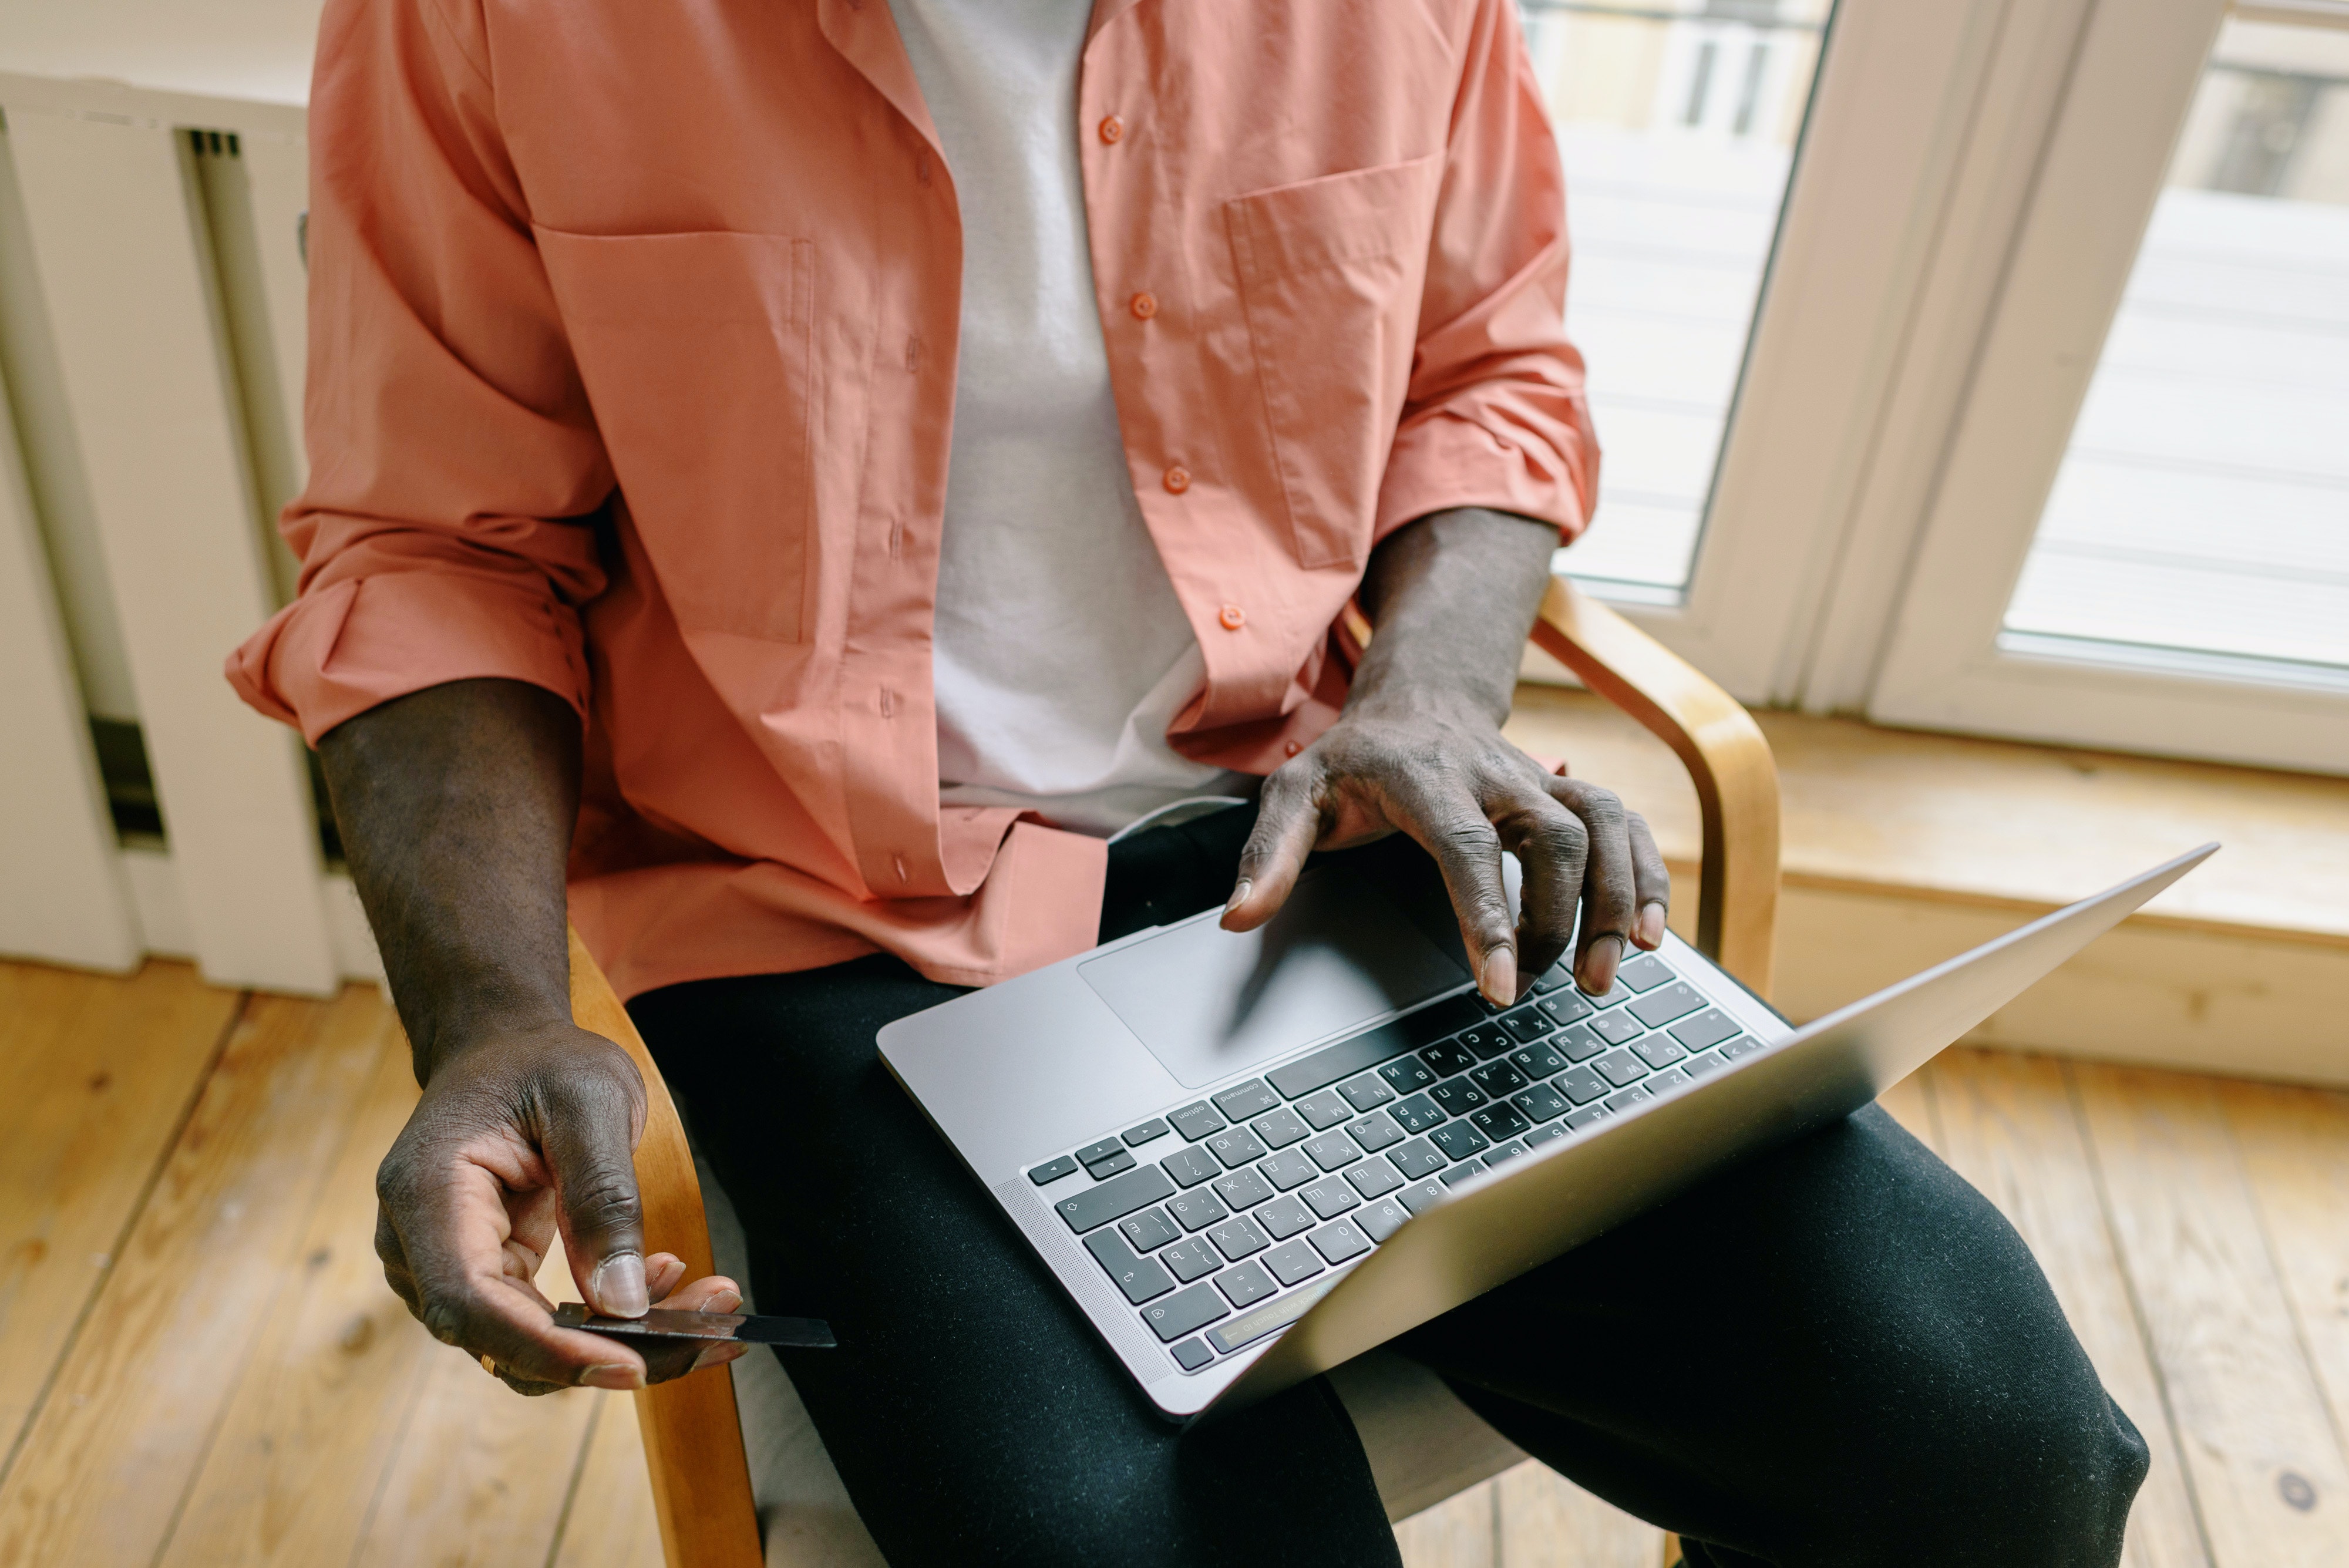
Can I use contactless ATMs with a foreign-issued contactless debit card?
Traveling abroad or sending money home? You might wonder: “Can I use contactless ATMs with a foreign-issued contactless debit card?” The short answer is: it depends—but often, yes. Many modern ATMs worldwide now support EMV chip and contactless (NFC) standards, especially in Europe, Canada, Australia, and major Asian cities. However, compatibility hinges on three factors: your card’s network (Visa, Mastercard), the ATM’s acceptance of international cards, and whether your issuing bank has enabled overseas contactless functionality. For remittance customers, this matters—especially if you’re withdrawing funds sent via digital transfer services. While contactless ATM withdrawals offer speed and convenience, not all foreign-issued cards are activated for tap-to-withdraw abroad. Always check with your bank before travel and confirm PIN requirements, as most contactless ATM transactions still require PIN verification for security. Pro tip: If contactless fails, fallback to chip-and-PIN. Also, consider using remittance apps that partner with local ATM networks—they often offer better exchange rates and lower withdrawal fees than standard bank ATMs. Stay informed, test early, and choose trusted providers to maximize efficiency and minimize costs when accessing your hard-earned funds overseas.Are there contactless ATMs that support voice-guided or accessible interfaces?
Yes, contactless ATMs with voice-guided and accessible interfaces are increasingly available—and they’re transforming financial inclusion for remittance senders and receivers. These ATMs support features like audio instructions, braille keypads, screen reader compatibility, adjustable font sizes, and hands-free navigation—critical for visually impaired, elderly, or neurodiverse users. For remittance businesses, partnering with banks or ATM networks that deploy such inclusive technology strengthens trust and expands market reach. Migrant workers, seniors, and people with disabilities often rely on cash pickups; accessible ATMs ensure they can independently and safely withdraw funds without assistance—reducing transaction friction and abandonment. Leading providers—including Citibank, Chase, and several European institutions—now roll out ADA-compliant, contactless ATMs that accept QR-based withdrawals and offer multilingual voice guidance. Some even integrate with remittance apps to trigger step-by-step audio prompts upon scanning a transaction code. As global regulators emphasize digital accessibility (e.g., EU’s EN 301 549, U.S. ADA standards), remittance firms prioritizing inclusive ATM access gain competitive advantage, improve compliance, and align with ESG goals. Investing in or promoting these solutions signals commitment to equitable financial services—driving loyalty and long-term growth.Which grocery stores or convenience chains have contactless ATMs on-site?
Many remittance customers rely on convenient, secure cash access—especially when receiving international transfers. Contactless ATMs at major grocery stores and convenience chains offer a fast, hygienic way to withdraw funds without physical card insertion or keypad contact. Walmart, Kroger, and 7-Eleven are among the top U.S. retailers deploying contactless-enabled ATMs through partnerships with networks like Allpoint, MoneyPass, and Cardtronics. These ATMs support tap-to-pay via NFC-enabled debit cards and mobile wallets (Apple Pay, Google Pay), aligning with growing consumer demand for touch-free financial services. For remittance businesses, integrating with these ATM networks means faster payout options and enhanced customer satisfaction. By promoting “cash pickup at trusted local stores,” you reduce friction for recipients who prefer immediate, no-bank-account access—especially immigrants, gig workers, and underbanked users. Always verify ATM compatibility: not all store-located machines support contactless functionality yet. Check your remittance partner’s supported network coverage and ensure real-time balance updates and low withdrawal fees. Highlighting contactless ATM access in your marketing builds trust and positions your service as modern, safe, and user-centric.Do contactless ATMs require NFC-enabled smartphones—or just contactless cards?
Do contactless ATMs require NFC-enabled smartphones—or just contactless cards? For remittance businesses, understanding this distinction is critical to optimizing cash-out options for recipients. Contactless ATMs are designed primarily to accept contactless debit or credit cards—those embedded with EMV chip and radio-frequency (RF) technology—not smartphones. These cards communicate via short-range RFID (13.56 MHz), the same standard used in most contactless payment terminals.While some newer ATMs support smartphone-based withdrawals via QR codes or bank-specific apps, true NFC-based smartphone withdrawal at ATMs remains rare and highly dependent on regional banking infrastructure and proprietary integrations—not universal NFC compatibility. Most remittance recipients still rely on physical contactless cards issued by partner banks or e-money providers.This matters because remittance operators must prioritize card issuance partnerships and ensure recipient cards meet ISO/IEC 14443 standards—not smartphone specifications. Promoting “NFC phone” access can mislead customers and create friction where cards work reliably. By focusing on interoperable contactless cards—and clear instructions for card-based ATM use—remittance services boost cash-out speed, reduce failed transactions, and improve financial inclusion in underserved markets.Always verify local ATM capabilities before launching card-based payout channels. When in doubt, default to contactless card compatibility—it’s proven, scalable, and widely supported across emerging economies.
About Panda Remit
Panda Remit is committed to providing global users with more convenient, safe, reliable, and affordable online cross-border remittance services。
International remittance services from more than 30 countries/regions around the world are now available: including Japan, Hong Kong, Europe, the United States, Australia, and other markets, and are recognized and trusted by millions of users around the world.
Visit Panda Remit Official Website or Download PandaRemit App, to learn more about remittance info.
Latest News
2026-10-12 23:36