USD to EUR Conversion Guide: Cash, Costs, Inflation, Tuition, Accounts, Forex, Compliance & API
GPT_Global - 2026-10-20 14:04:17.0 0
Can I convert USD to EUR without a bank account—using only cash or prepaid cards?
Yes, you can convert USD to EUR without a bank account—using only cash or prepaid cards. Many licensed remittance providers and currency exchange services offer this convenient option for travelers, expats, and unbanked individuals. Cash-to-EUR exchanges are widely available at airport kiosks, local bureaux de change, and authorized agents worldwide. Simply present your USD cash and receive EUR notes instantly—no bank verification or account required. Fees and exchange rates vary, so always compare providers using real-time tools before transacting. Prepaid travel cards are another smart alternative. Load them with USD online or in person, then lock in favorable EUR exchange rates before departure. Top remittance platforms like Wise, Revolut, and Western Union offer reloadable multi-currency cards usable at ATMs and point-of-sale terminals across Europe. While convenient, cash exchanges may carry higher margins than digital transfers, and prepaid cards often have activation or inactivity fees. Always check regulatory compliance—choose only FCA-, FinCEN-, or BaFin-licensed providers to ensure safety and transparency. For fast, low-cost USD-to-EUR conversion without a bank account, trusted remittance partners deliver flexibility, speed, and security—empowering seamless cross-border money movement anytime, anywhere.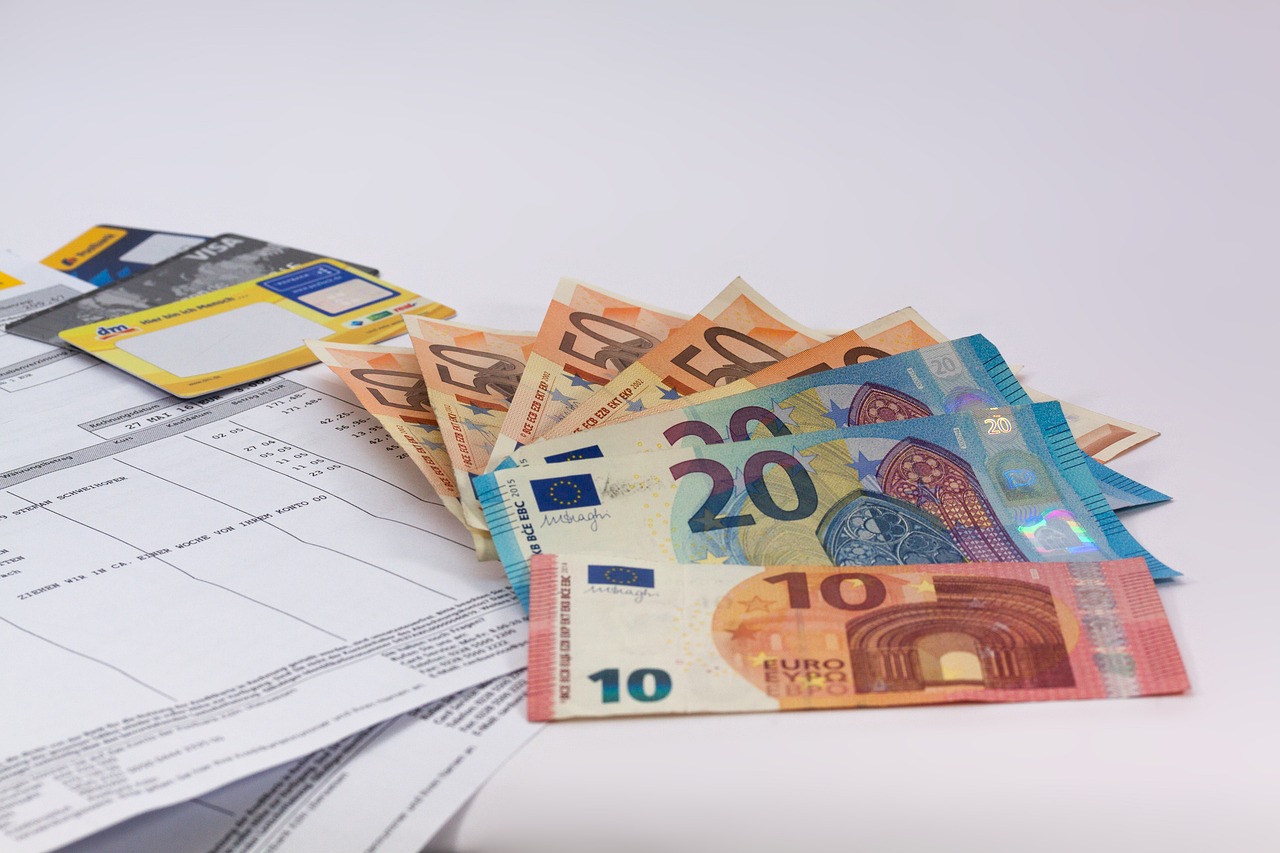
How do I calculate the total cost—including spreads and fees—of converting $10,000 USD to EUR?
Calculating the total cost of converting $10,000 USD to EUR goes beyond the advertised exchange rate. Hidden spreads and fees can significantly impact your final amount—often costing hundreds more than expected. Many traditional banks and outdated remittance services widen the spread (the gap between the mid-market rate and their offered rate) instead of charging transparent fees. To get an accurate total cost, start with the real-time mid-market rate (check XE or Reuters). Then compare it to the rate the provider offers for your $10,000 transfer. The difference—multiplied by $10,000—is your spread cost. Next, add any fixed fees (e.g., $15 wire fee or €5 receiving fee). Some providers also charge intermediary bank fees (€15–€30), which reduce the EUR received. For example: At a mid-market rate of 0.9300, $10,000 equals €9,300. If a provider offers 0.9150, your EUR drops to €9,150—costing €150 in spread alone. Add a $20 fee (~€18.60), and total cost exceeds €168. Transparent fintech remittance platforms often offer near-mid-market rates and flat, upfront fees—saving you 40–70% versus banks. Always request a full cost breakdown before sending. With smart comparison and trusted digital remittance partners, you keep more of your money—every time you convert USD to EUR.What impact does inflation in the U.S. and Eurozone have on USD/EUR conversion value?
Understanding how inflation affects currency values is crucial for anyone sending money across borders—especially from the U.S. to Europe. When U.S. inflation rises faster than in the Eurozone, the Federal Reserve often hikes interest rates to curb price growth. Higher U.S. rates typically strengthen the USD relative to the EUR, making each dollar buy more euros. Conversely, if Eurozone inflation surges while U.S. inflation cools, the European Central Bank may tighten policy, potentially boosting the euro and lowering the USD/EUR exchange rate. For remittance customers, even small shifts in the USD/EUR rate significantly impact how much recipients receive. A stronger dollar means more euros per dollar sent—better value for U.S.-based senders. But volatility driven by divergent inflation trends can erode savings if transfers aren’t timed strategically. At [Your Remittance Business], we monitor real-time inflation data and central bank signals to offer competitive, transparent exchange rates—and optional rate alerts—to help you lock in favorable USD/EUR conversions. Avoid hidden fees and outdated mid-market rates: choose a service built on economic insight and customer-first transparency.How do I convert USD to EUR for a tuition payment to a university in Germany?
Converting USD to EUR for a tuition payment to a German university requires accuracy, speed, and cost-efficiency. Many students and families mistakenly rely on traditional banks—only to face hidden fees, poor exchange rates, and slow processing times. Specialized remittance services offer transparent, competitive EUR exchange rates and low flat fees—often saving up to 3–5% compared to banks. Look for platforms with SEPA (Single Euro Payments Area) compliance, ensuring your EUR funds arrive directly in the university’s German bank account within 1–2 business days. Before sending, verify the university’s exact banking details: IBAN, BIC/SWIFT, and tuition reference number. Some institutions require payments labeled with student ID or invoice numbers to ensure proper crediting—always confirm this to avoid delays or misallocation. Regulated remittance providers also offer real-time rate tracking, scheduled transfers, and multi-currency accounts—ideal for managing recurring semester payments. Plus, most integrate secure encryption and comply with both U.S. FinCEN and EU PSD2 regulations for peace of mind. For stress-free, low-cost USD-to-EUR tuition payments, choose a licensed remittance partner with dedicated student support, clear fee breakdowns, and proven delivery to German universities. Start your transfer today—and pay tuition confidently, not expensively.Is it legal for U.S. residents to hold EUR savings accounts—and how do I fund one with USD?
Yes, U.S. residents can legally hold EUR savings accounts—but not with most domestic banks. While U.S. financial institutions typically don’t offer foreign-currency savings accounts to individuals, specialized international banks, fintech platforms, and offshore-friendly institutions do. Always verify the provider’s regulatory compliance (e.g., FDIC-equivalent coverage abroad or proper licensing) and report foreign accounts exceeding $10,000 USD to the IRS via FBAR (FinCEN Form 114). Funding a EUR account with USD is straightforward through licensed remittance services. Reputable providers offer competitive mid-market exchange rates, low fees, and fast conversion—often within seconds. Simply initiate a USD transfer, select EUR as the destination currency, and provide your EUR account details (IBAN, BIC/SWIFT). Many platforms also support recurring transfers and multi-currency wallets for seamless management. Why go EUR? Hedge against USD volatility, earn higher interest in some EU jurisdictions, or prepare for travel, relocation, or business in the Eurozone. With secure, compliant, and transparent remittance solutions, converting and saving in EUR has never been easier—or more strategic—for U.S. residents.How do forex brokers quote USD-to-EUR—bid, ask, and spread explained simply?
When sending money from the US to Europe, understanding how forex brokers quote USD-to-EUR is essential to get the best exchange rate—and avoid hidden costs. Brokers display two prices: the *bid* (what they’ll pay you for EUR) and the *ask* (what they charge you for EUR). For example, a quote of 0.9250/0.9270 means you’ll receive €0.9250 per $1 when selling EUR, but pay $1.0785 per €1 when buying EUR (since 1 ÷ 0.9270 ≈ 1.0785). The difference between bid and ask—the *spread* (here, 0.0020 or 20 pips)—is how brokers earn revenue. A narrower spread usually signals better value, especially for larger remittances. Some providers mask fees in wide spreads instead of charging transparent fees—so always compare the *mid-market rate* (the true interbank rate) against what’s offered. At [Your Remittance Business], we use real-time mid-market rates and charge a low, upfront fee—no hidden spreads. That means more euros reach your recipient faster and fairly. Whether you’re supporting family or paying bills abroad, transparency and speed matter. Before sending, check live USD/EUR quotes, read the fine print, and choose a licensed provider with strong EU/US compliance. Smart remitting starts with knowing how forex pricing really works.What documentation is required to convert more than $10,000 USD to EUR at a traditional bank?
Converting more than $10,000 USD to EUR at a traditional bank triggers strict anti-money laundering (AML) and Know Your Customer (KYC) requirements. U.S. law mandates banks to file a Currency Transaction Report (CTR) with FinCEN for any cash transaction exceeding $10,000 — though wire transfers are exempt from CTRs, enhanced due diligence still applies. You’ll typically need government-issued ID (e.g., passport or driver’s license), proof of address (e.g., utility bill or bank statement less than 3 months old), and documentation verifying the source of funds — such as recent pay stubs, tax returns, or sale agreements. Banks may also request a signed declaration explaining the purpose of the conversion (e.g., property purchase, tuition, or business investment). Processing times can extend beyond 24–48 hours due to compliance reviews, and fees often include both foreign exchange margins and fixed transfer charges — sometimes totaling 3–5% above mid-market rates. For frequent or larger conversions, specialized remittance providers offer faster execution, transparent pricing, and dedicated support — all while remaining fully regulated and compliant. Before initiating your transfer, compare options using real-time rate calculators and verify regulatory licenses (e.g., FinCEN MSB registration, FCA or BaFin authorization). Choosing a trusted, compliant partner ensures security, speed, and cost-efficiency — especially when moving significant sums across borders.How can developers programmatically fetch live USD-to-EUR exchange rates via API?
For remittance businesses, accessing real-time USD-to-EUR exchange rates is critical for transparency, competitive pricing, and regulatory compliance. Programmatically fetching live rates via RESTful APIs eliminates manual updates and reduces margin errors—ensuring customers receive accurate, up-to-the-second conversions. Popular, developer-friendly APIs like ExchangeRate-API, CurrencyLayer, and the European Central Bank’s (ECB) free XML/JSON feed provide reliable USD/EUR data. Most require simple HTTP GET requests with an API key; for example: `GET https://api.exchangerate-api.com/v4/latest/USD` returns JSON with the current EUR rate under `rates.EUR`. Developers can integrate this into backend services using Python, Node.js, or PHP in under 10 lines of code. Security and reliability matter: choose APIs with HTTPS, rate limiting, and uptime SLAs. For production remittance platforms, cache responses briefly (e.g., 30–60 seconds) to balance freshness and performance—while always displaying the timestamped rate to users before transaction confirmation. This builds trust and meets PSD2 and FX transparency guidelines. By automating rate retrieval, remittance providers improve operational efficiency, reduce FX risk exposure, and enhance customer experience—turning accurate, real-time data into a strategic advantage in a competitive cross-border payments landscape.
About Panda Remit
Panda Remit is committed to providing global users with more convenient, safe, reliable, and affordable online cross-border remittance services。
International remittance services from more than 30 countries/regions around the world are now available: including Japan, Hong Kong, Europe, the United States, Australia, and other markets, and are recognized and trusted by millions of users around the world.
Visit Panda Remit Official Website or Download PandaRemit App, to learn more about remittance info.
Latest News
2026-10-21 00:30
2026-10-21 00:30