CHF/USD Exchange Rate Explained: Travel Cards, Interbank Rates, Geopolitics & Real-Time Accuracy
GPT_Global - 2026-11-04 10:07:15.0 22
How do travel money cards handle the CHF-to-USD conversion for small amounts (e.g., ≤10 CHF)?
Travel money cards offer a convenient solution for converting Swiss Francs (CHF) to US Dollars (USD), even for small transactions—such as amounts ≤10 CHF. Unlike traditional banks or airport kiosks, most reputable travel cards apply transparent, mid-market exchange rates with low or no markup on micro-transactions. For tiny CHF amounts, card issuers typically round conversions to the nearest cent in USD, avoiding punitive minimum fees that plague many remittance services. Some cards absorb minor rounding differences, while others display real-time conversion before confirmation—giving users full visibility and control. This precision matters: frequent small purchases (e.g., coffee, transit tickets) add up. With travel money cards, you avoid dynamic currency conversion (DCC) traps at point-of-sale terminals—a common source of hidden 3–5% surcharges when paying in CHF abroad. Moreover, top remittance-focused cards (like Revolut, Wise, or N26 Travel) allow multi-currency top-ups in CHF and instant auto-conversion to USD at competitive interbank rates—ideal for travelers needing flexibility without sacrificing value on micro-transactions. Choosing a card with no foreign exchange fee on small conversions ensures cost-efficiency and trust. Always compare rate transparency, rounding policies, and ATM withdrawal terms—because when it comes to CHF-to-USD for ≤10 CHF, fairness starts with clarity.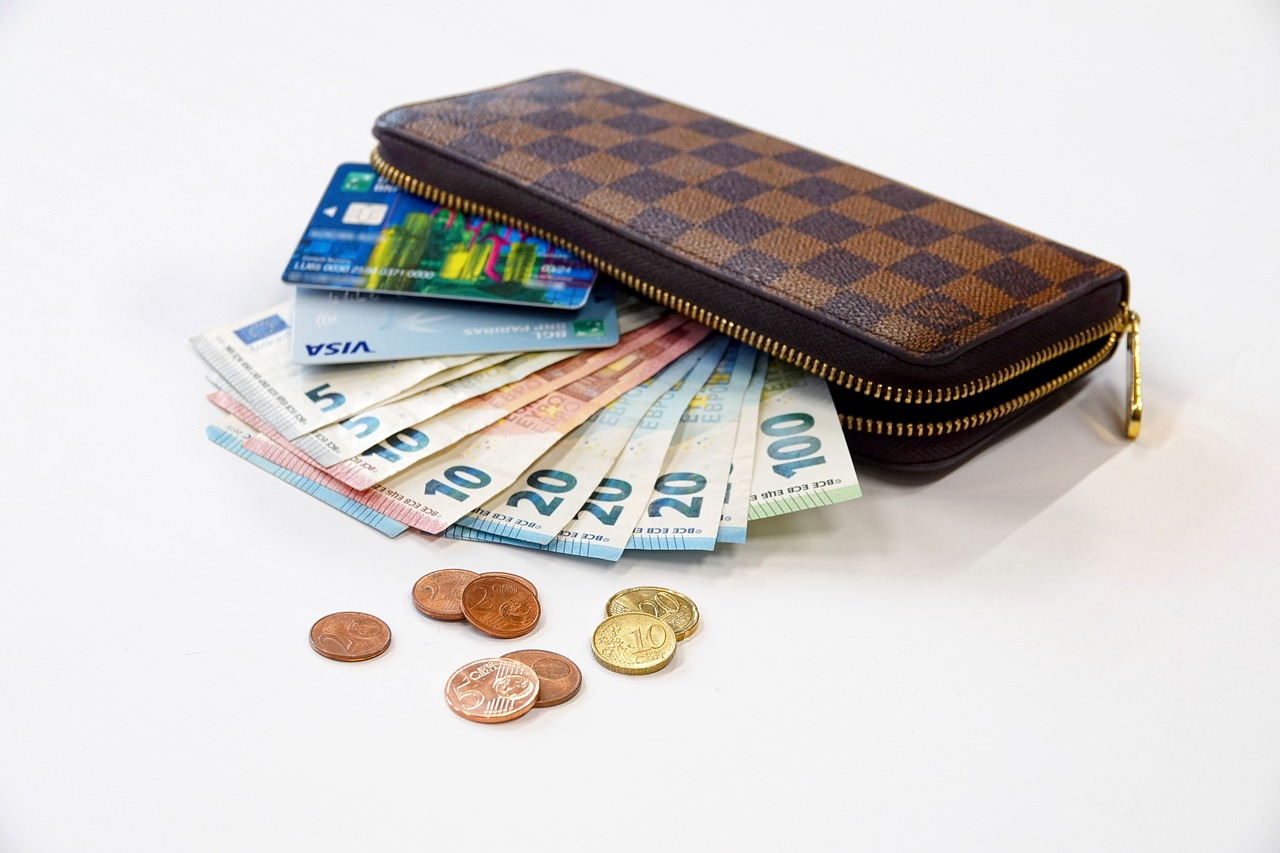
What’s the interbank rate for 1 CHF to USD, and who has access to it?
Understanding the interbank rate for 1 CHF to USD is essential for anyone sending money between Switzerland and the United States. The interbank rate—also known as the mid-market or wholesale rate—is the real-time exchange rate at which large financial institutions trade currencies among themselves. As of today, it hovers around 1.12–1.14 USD per CHF, though it fluctuates constantly due to market forces like interest rates, inflation, and geopolitical events. This rate is not publicly listed on consumer platforms; instead, it’s accessible only to banks, central banks, and licensed financial institutions operating in the interbank foreign exchange market. Remittance providers rarely offer this exact rate—they apply a transparent markup to cover operational costs and margin. Savvy customers should compare both the exchange rate *and* fees across services to identify the true cost of their transfer. For remittance businesses, leveraging near-interbank rates—especially through partnerships with liquidity providers or FX aggregators—enhances competitiveness and builds trust. Offering rate transparency, real-time tracking, and low-margin conversions helps attract Swiss and U.S.-based clients seeking fairness and speed. Always disclose your margin clearly: it’s not just ethical—it’s a key SEO differentiator in search results for “CHF to USD transfer” or “best Swiss franc exchange rate.”Does the CHF/USD exchange rate behave differently during US market hours vs. European/Swiss hours?
Understanding CHF/USD exchange rate behavior across trading sessions is vital for remittance businesses sending funds between Switzerland and the U.S. The currency pair exhibits notable volatility differences: during European/Swiss market hours (6 a.m.–3 p.m. CET), CHF/USD tends to be more stable and liquidity-driven, reflecting Swiss National Bank interventions and regional economic data. In contrast, U.S. market hours (8:30 a.m.–5:30 p.m. EST) often bring sharper moves—especially around U.S. CPI, Fed announcements, or NFP releases—amplifying spreads and slippage risk for money transfer operators. For remittance providers, timing matters. Sending bulk CHF-to-USD transfers during overlapping London–New York hours (1 p.m.–5 p.m. CET / 8 a.m.–12 p.m. EST) typically offers tighter spreads and deeper liquidity. Conversely, off-peak windows—like late-night Swiss or early-morning U.S. hours—may trigger wider margins due to lower participation and algorithmic hedging constraints. Smart remittance platforms now leverage real-time session analytics to auto-optimize execution windows—reducing FX cost by up to 0.3% per transaction. By aligning payout schedules with high-liquidity CHF/USD windows, businesses improve margin predictability and enhance customer trust through transparent, competitive rates. Monitor session clocks—not just time zones—to stay ahead.How do geopolitical events (e.g., EU tensions, Swiss referendums) impact short-term CHF/USD movement?
Geopolitical events significantly influence short-term CHF/USD movements—critical knowledge for remittance businesses sending money to or from Switzerland. The Swiss franc (CHF) is a traditional safe-haven currency, meaning it often strengthens abruptly during EU tensions, Eurozone instability, or global uncertainty. For instance, escalating disputes over EU-Swiss bilateral agreements—or unexpected outcomes of Swiss referendums on immigration, taxation, or EU alignment—can trigger rapid CHF appreciation. A “no” vote in a referendum perceived as increasing economic isolation may spark capital inflows into CHF assets, pushing CHF/USD down (i.e., fewer USD needed per CHF), impacting exchange rates mid-transaction. Remittance providers must monitor real-time geopolitical catalysts and integrate agile FX risk tools—like forward contracts or rate alerts—to protect margins and offer competitive, transparent pricing. Delayed reaction can mean margin erosion or customer dissatisfaction when rates shift unexpectedly. Partnering with FX providers offering geopolitical intelligence dashboards and automated hedging helps remittance firms stay proactive—not reactive. Understanding these dynamics isn’t just about forecasting; it’s about building trust through predictability and value in every cross-border transfer.Is there a forward rate for CHF/USD for 3-month or 6-month delivery—and how is it calculated?
Yes, there is a forward rate for CHF/USD for both 3-month and 6-month delivery—essential for remittance businesses managing cross-border payments to and from Switzerland and the U.S. These forward rates hedge against exchange rate volatility, ensuring predictable costs and margins. The CHF/USD forward rate is calculated using the spot rate plus or minus a forward points adjustment, derived from the interest rate differential between Swiss francs (governed by SNB policy) and U.S. dollars (influenced by the Fed’s rates). The formula: Forward Rate = Spot Rate × [(1 + iUSD × t/360) / (1 + iCHF × t/360)], where *t* is days to maturity (e.g., 90 for 3 months, 180 for 6 months). For remittance providers, locking in forward rates lets them quote fixed CHF-to-USD exchange rates to customers weeks in advance—boosting trust and reducing settlement risk. Real-time forward pricing is available via interbank platforms or integrated FX APIs used by modern remittance platforms. Monitoring CHF/USD forward points also reveals market expectations: widening premiums may signal anticipated USD strength or SNB intervention. Smart remittance operators use this insight to optimize hedging strategies and improve margin stability—especially critical amid current monetary policy divergence.How accurate are mobile banking apps when showing “1 CHF = ? USD” for instant transfers?
Mobile banking apps often display “1 CHF = ? USD” exchange rates for instant transfers—but accuracy varies significantly. Many apps show mid-market rates *for reference only*, while applying hidden markups (0.5%–4%) during actual transactions. This discrepancy can cost users tens or even hundreds of dollars on larger remittances. For remittance businesses, transparency is a key differentiator. Unlike generic banking apps that prioritize convenience over fairness, specialized remittance platforms leverage real-time interbank data and disclose all fees upfront—ensuring the rate you see is the rate you get. Regulatory compliance (e.g., FINMA in Switzerland, CFPB in the U.S.) further strengthens trust in licensed providers. Consumers should always compare the “exchange rate margin” — not just transfer fees. A 1.2% markup on CHF 5,000 equals ~USD 60 lost versus a true mid-market rate. Reputable remittance services minimize this gap with dynamic pricing engines and zero-spread options for high-volume senders. Choosing accuracy over speed pays off: verified mid-market rates, full fee breakdowns, and instant FX confirmation help Swiss expats, freelancers, and SMEs maximize value. For your next CHF-to-USD transfer, skip the bank app’s estimate—and opt for a regulated remittance partner built for precision.What role does gold reserves or Swiss neutrality play in CHF strength versus the USD?
Gold reserves and Swiss neutrality are foundational pillars supporting the Swiss Franc’s (CHF) reputation as a global safe-haven currency—critical context for remittance businesses operating across volatile markets. With over 1,000 tonnes of gold held by the Swiss National Bank (SNB), these reserves reinforce CHF stability, confidence, and liquidity during geopolitical or financial stress.Swiss neutrality—unchallenged for over 200 years—further enhances trust in CHF-denominated transactions. Unlike many currencies tied to military alliances or fiscal deficits, the CHF benefits from perceived political insulation, attracting capital flows during crises. This reliability translates directly to lower volatility and tighter spreads for CHF/USD transfers.For remittance providers, understanding this dynamic means offering CHF payouts with greater predictability, reduced hedging costs, and enhanced client confidence—especially for high-net-worth individuals and institutions seeking stability. Real-time CHF exchange rates often reflect safe-haven demand spikes, presenting strategic opportunities for timing transfers.Moreover, SNB’s conservative monetary policy and strong current account surplus reinforce CHF resilience versus the USD—even amid U.S. inflation or Fed rate shifts. Leveraging CHF’s structural strengths allows remittance firms to differentiate services, improve margin control, and build long-term trust in cross-border payments. Stay informed, stay competitive.If the USD strengthens significantly, what would 1 CHF likely be worth in USD — and what triggers such a shift?
When the USD strengthens significantly, the Swiss Franc (CHF) typically weakens in USD terms—meaning 1 CHF buys fewer US dollars. Historically, 1 CHF trades near parity with the USD (e.g., $0.90–$1.10), but a sharp USD rally—driven by aggressive Federal Reserve rate hikes, robust U.S. economic data, or global risk-off sentiment—can push the exchange rate to $0.85 or lower. For remittance businesses and customers sending money from the U.S. to Switzerland (or vice versa), this shift directly impacts transfer value and fees. Key triggers behind such USD strength include rising U.S. Treasury yields, widening interest rate differentials with the Swiss National Bank (which maintains ultra-low or negative rates), geopolitical instability boosting USD demand as a safe haven, and relative inflation trends favoring the U.S. dollar. For remittance providers, monitoring real-time FX movements is critical—not just for competitive pricing, but to advise clients on optimal send windows. Transparent mid-market rate displays, low-margin FX markups, and forward contracts can help mitigate volatility risks. Staying ahead of macro drivers empowers both businesses and end-users to make smarter, cost-effective cross-border transfers—especially when the CHF/USD pair moves sharply.
About Panda Remit
Panda Remit is committed to providing global users with more convenient, safe, reliable, and affordable online cross-border remittance services。
International remittance services from more than 30 countries/regions around the world are now available: including Japan, Hong Kong, Europe, the United States, Australia, and other markets, and are recognized and trusted by millions of users around the world.
Visit Panda Remit Official Website or Download PandaRemit App, to learn more about remittance info.
Latest News


2026-11-04 11:04