CHF to INR Transfer Guide: Wise vs Remitly Fees, PayPal Rates, Interbank vs Retail, Google Finance Alerts & FEMA Compliance
GPT_Global - 2026-09-15 17:05:23.0 13
How do money transfer services like Wise, Remitly, or InstaReM compare on CHF→INR fees?
When sending money from Swiss Francs (CHF) to Indian Rupees (INR), choosing the right remittance service can save you significant fees and improve exchange rate value. Wise, Remitly, and InstaReM (now part of Wallex) each offer competitive CHF→INR transfers—but with key differences. Wise stands out for transparency and mid-market exchange rates, charging a low, upfront fee—typically 0.3–0.7% for CHF→INR, plus a small fixed fee (e.g., CHF 1.25). Funds usually arrive in INR within 1 business day to bank accounts or UPI via partnered banks. Remitly offers both “Economy” (lower fee, 1–3 days) and “Express” (higher fee, minutes) options. Its CHF→INR fees range from CHF 1.99 to CHF 3.99, with exchange rates slightly less favorable than Wise’s—often adding 0.5–1.0% hidden margin. InstaReM (now Wallex) emphasizes zero-margin FX but may apply a minimal processing fee (CHF 0.50–CHF 2.00); however, its INR payout network is more limited in India compared to Wise or Remitly, potentially affecting speed or accessibility. For cost-conscious senders prioritizing value and speed, Wise generally leads on CHF→INR transfers. Remitly suits users needing instant cash pickup or UPI, while Wallex appeals to high-volume corporate clients. Always compare live rates and total cost—including fees and exchange rate markup—before sending.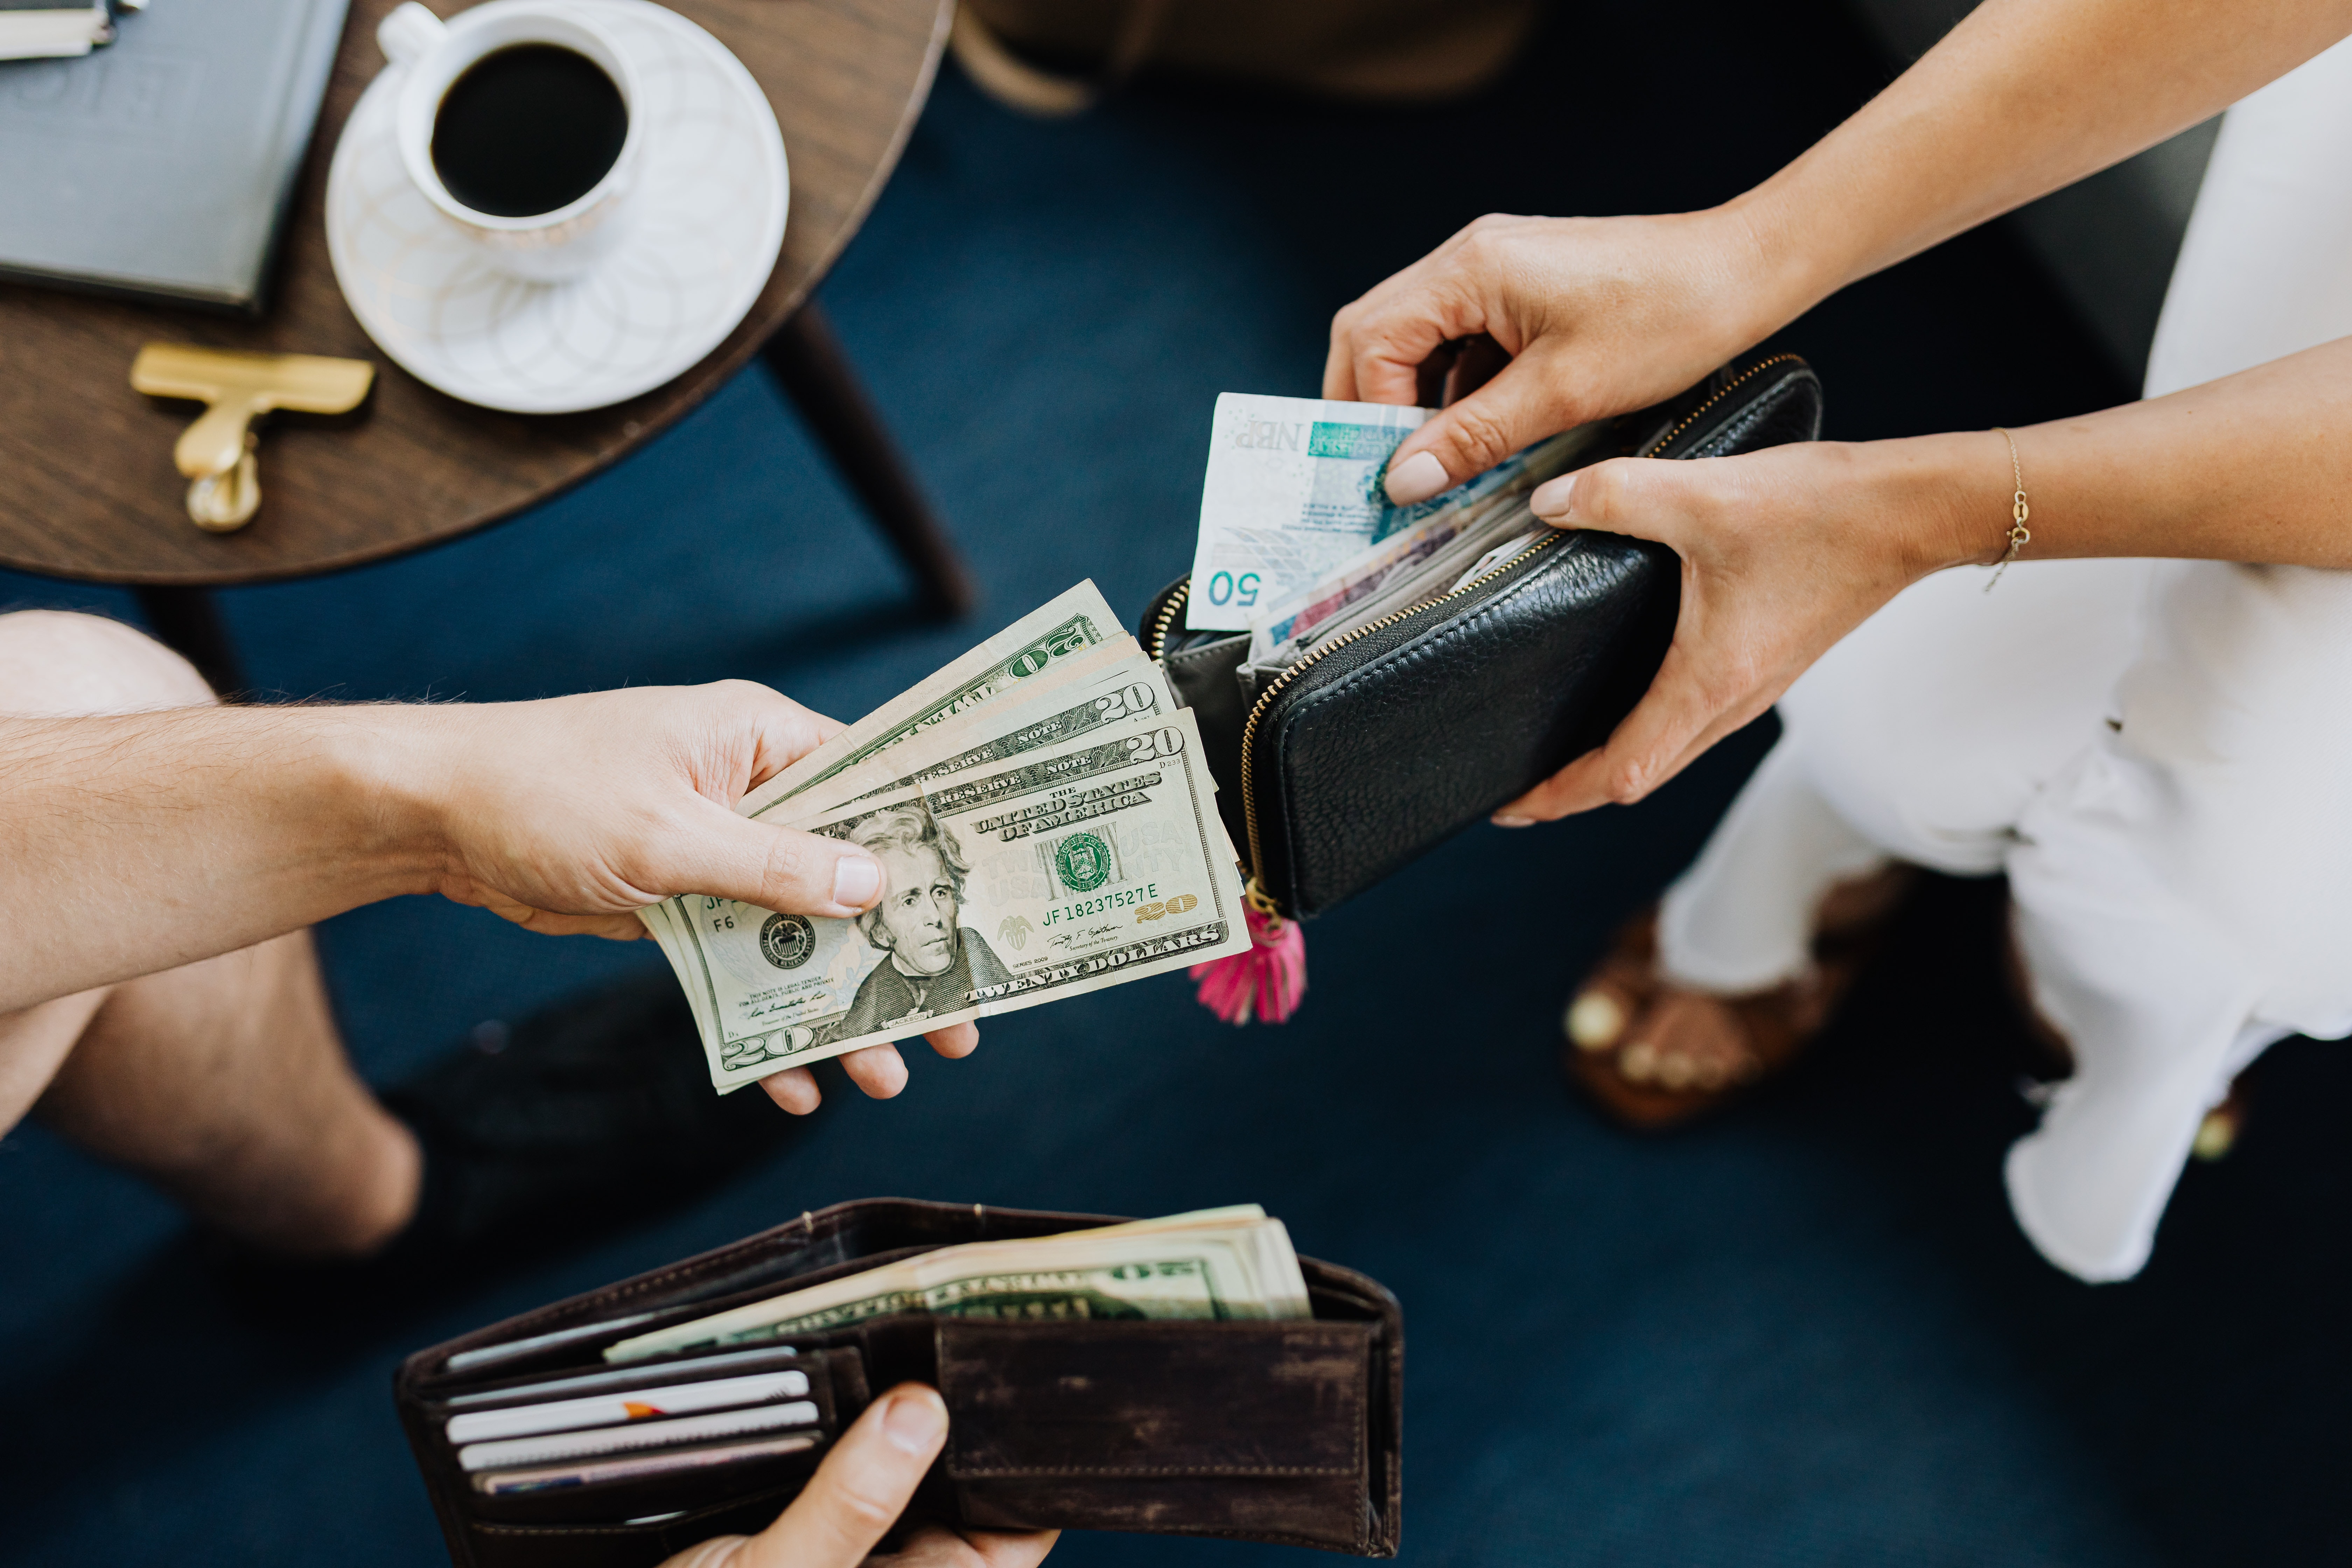
Does PayPal apply a fixed or dynamic CHF to INR conversion rate—and how transparent is it?
When sending money from Switzerland to India, understanding PayPal’s CHF to INR conversion rate structure is critical for cost-effective remittances. PayPal uses a **dynamic, market-based exchange rate**, not a fixed one—meaning the rate fluctuates in real time based on interbank FX markets, plus a built-in markup (typically 2–4% above mid-market). This lack of a fixed rate offers flexibility but reduces predictability for senders. Transparency remains a key concern: PayPal displays the applied rate *only after* initiating a transaction—not upfront during quote estimation. Users must proceed through several steps before seeing the final CHF-to-INR conversion and total fees, making it hard to compare with specialist remittance providers who show all-inclusive, real-time rates at the outset. For businesses and frequent senders, this opacity can mean hidden costs and suboptimal value. Leading remittance services offer transparent, mid-market or near-mid-market rates with flat, disclosed fees—often saving users 30–50% versus PayPal’s combined FX margin and service charges. Always compare using the full amount received in INR, not just the exchange rate displayed. Optimize cross-border payments by choosing platforms prioritizing rate clarity, low margins, and instant INR delivery—because in remittances, transparency isn’t optional—it’s essential.What is the CHF/INR interbank rate, and how does it differ from retail customer rates?
Understanding the CHF/INR interbank rate is essential for anyone sending money from Switzerland to India. The interbank rate is the wholesale exchange rate at which large financial institutions trade currencies among themselves—typically in high-volume, low-risk transactions. It reflects real-time market conditions and is generally the most favorable rate available. However, retail customers—including individuals and small businesses using remittance services—never receive the interbank rate. Instead, they’re quoted a retail rate that includes a built-in margin or markup. This spread compensates service providers for operational costs, risk management, and profit. Depending on the provider, the markup can range from 1% to over 4%, significantly impacting the final INR amount received. Transparent remittance businesses clearly disclose their exchange rate margin and fees upfront—helping customers compare value beyond just transfer speed or convenience. At [Your Remittance Brand], we minimize margins and offer near-interbank rates with no hidden charges, ensuring more rupees reach your family in India. Always check whether a provider shows the mid-market (interbank) rate alongside their offered rate. This simple step empowers smarter, cost-effective international transfers—and turns currency knowledge into real savings.How can I set up a rate alert for CHF to INR on Google Finance or XE?
Setting up a CHF to INR rate alert is a smart move for anyone sending money from Switzerland to India. While Google Finance doesn’t offer direct currency alert functionality, XE.com provides a free, reliable alternative—ideal for remittance customers tracking optimal transfer timing. To create a CHF/INR rate alert on XE: visit xe.com, search for “CHF to INR”, click “Set Rate Alert”, enter your target exchange rate and email address, then confirm. You’ll receive instant notifications when the rate hits your threshold—helping you lock in favorable terms and avoid costly fluctuations. Why does this matter for remittances? Even a 0.5% improvement in the CHF/INR rate can save hundreds of rupees on larger transfers. Proactive rate monitoring empowers customers to act decisively—especially during volatile periods like Swiss National Bank policy shifts or RBI interventions. At [Your Remittance Business Name], we integrate live XE-powered rate insights into our platform—and offer personalized rate alerts via SMS or WhatsApp. Our zero-fee transfers and mid-market rates mean more value reaches your loved ones in India. Start watching the CHF/INR rate today—and send smarter, not harder.Are there any restrictions on converting CHF to INR under FEMA regulations in India?
Yes, there are specific restrictions on converting CHF to INR under India’s Foreign Exchange Management Act (FEMA) regulations. FEMA, administered by the Reserve Bank of India (RBI), governs all foreign exchange transactions—including remittances—to ensure capital account stability and prevent money laundering. Indian residents can convert CHF to INR for permissible current account transactions—such as travel, education, medical expenses, or family maintenance—within the Liberalized Remittance Scheme (LRS) limit of USD 250,000 per financial year (approx. ₹2.1 crore). CHF conversions must be routed through authorized dealers (AD banks) or RBI-approved money changers; direct peer-to-peer or informal channels are prohibited. For non-resident Indians (NRIs) or persons of Indian origin (PIOs), additional rules apply: funds must originate from legitimate sources, and documentation like purpose certificates or invoices may be required for larger amounts. Suspicious or repetitive small-value transactions may trigger RBI scrutiny under anti-money laundering (AML) norms. Choosing a licensed remittance partner with real-time CHF–INR rates, transparent fees, and end-to-end compliance ensures faster, safer, and FEMA-compliant conversions. Always verify your provider’s AD status via the RBI’s official list to avoid regulatory risk and transaction delays.
About Panda Remit
Panda Remit is committed to providing global users with more convenient, safe, reliable, and affordable online cross-border remittance services。
International remittance services from more than 30 countries/regions around the world are now available: including Japan, Hong Kong, Europe, the United States, Australia, and other markets, and are recognized and trusted by millions of users around the world.
Visit Panda Remit Official Website or Download PandaRemit App, to learn more about remittance info.
Latest News


2026-09-19 02:30